As part of Dubai Arbitration Week 2026, organised by Shardul Amarchand Mangaldas & Co. and co-organised by Osborne Partners, a panel discussion, “Corporate Divorces: Post M&A Disputes and the Protections Available to Investors”, brought together leading legal practitioners and valuation professionals to examine the disputes that can arise at different stages of an M&A transaction, from preliminary negotiations and due diligence to post-closing claims, investor exits and shareholder remedies. The discussion was moderated by Shaneen Parikh, Partner, Shardul Amarchand Mangaldas & Co., alongside Montek Mayal, Partner and Practice Head — Asia & Middle East, Osborne Partners, who participated as co-moderator.
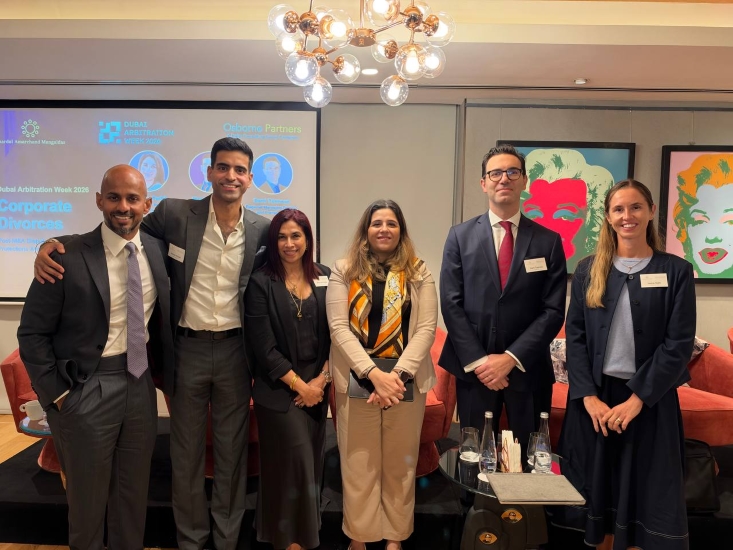
231e2[In picture from left to right: Chatura Randeniya, Montek Mayal, Shaneen Parikh, Khushboo Shahdadpuri, Sami Tannous, Ivana Dahl]
The panellists included Sami Tannous, Regional Managing Partner for MENA and Partner in Freshfields’ International Arbitration Group; Chatura Randeniya, Partner, Afridi & Angell; Khushboo Shahdadpuri, Partner, Al Tamimi & Co.; and Ivana Dahl, Legal Counsel, ADNOC Group.
The discussion highlighted how differences in valuation expectations, contractual interpretation, business performance and exit arrangements can develop into disputes after a transaction. It also examined the protections available to investors and the importance of addressing potential areas of disagreement while negotiating and drafting transaction documents.
Deal uncertainty and contractual allocation of risk
Opening the discussion, Shaneen Parikh observed that periods of significant deal activity are often followed by post-closing disputes, particularly where macroeconomic volatility, regulatory changes and valuation pressures widen the gap between the parties’ expectations and the eventual performance of the business. Tracing the global M&A cycle, she referred to the post-pandemic boom in 2021, followed by a sharp decline in 2023 amid rising interest rates and geopolitical fractures. This was followed by a recovery, with reports indicating that global M&A deal values had exceeded 5.6 trillion in 2025. She observed that larger transactions also meant more was at stake when deals did not proceed as expected.
She also highlighted how deferred consideration, earn-outs and post-closing price adjustments are used to bridge differences in valuation expectations. However, below-target performance, disagreements over accounting methodology and failure to achieve milestones can subsequently give rise to purchase price adjustment and clawback claims.
Addressing whether geopolitical developments and market uncertainty were making transactions harder to complete, Khushboo Shahdadpuri observed that companies have different appetites for risk. She did not necessarily agree that deals were becoming harder to close, explaining that changing geopolitical circumstances could instead lead to different market participants entering the investment landscape, depending on their investment strategies and risk appetite.
She shared an example of an alternative cost model implemented for a client during the regional crisis. The model involved a fixed-fee component and a moving target cost, with gains arising from cost underruns and losses arising from cost overruns shared between the parties. The arrangement was intended to distribute risk more fairly and required valuation experts to help determine the target cost.
Ms. Shahdadpuri also discussed force majeure and hardship under GCC-governed contracts. She distinguished between force majeure as a contractual provision and the legal principle under civil law, explaining that the latter generally requires the relevant obligation to have become totally impossible to perform. Referring to disputes arising from the blockade involving Qatar, Egypt, the UAE, Saudi Arabia and Bahrain, she noted that tribunals had, in some cases, declined to accept force majeure because alternative routes remained available, even if they involved additional time and expense.
She further referred to the concept of exceptional circumstances under UAE law, which may permit a rebalancing of obligations between parties. However, the extent of that rebalancing is ultimately for the tribunal to determine.
Term sheets and obligations during negotiations
The panel next considered disputes that can arise even before a definitive transaction agreement is executed. Chatura Randeniya observed that the preliminary stage of an M&A transaction can itself become a source of disputes, particularly because parties may incur substantial legal and advisory costs during due diligence before entering into a binding agreement.
He explained that term sheets and preliminary documents frequently contain a combination of binding and non-binding provisions. As negotiations progress, business teams may begin acting as though the transaction has already been concluded, even though certain matters remain unresolved.
Mr. Randeniya compared the common law and civil law approaches to pre-contractual negotiations. She noted that common law does not generally recognise a duty to negotiate in good faith, whereas the UAE’s onshore civil law framework has introduced express obligations in this regard.
He highlighted the important questions arising at the preliminary stage, including whether a binding agreement has been formed, whether a party can be held liable for walking away from negotiations in bad faith, and what information must be disclosed and protected during negotiations.
On the formation of contracts, he explained that both common law and civil law systems recognise the importance of offer, acceptance and a meeting of minds. However, parties do not necessarily have to agree on every aspect of a transaction for a binding contract to arise. Under the onshore UAE framework, a contract may be formed where the parties have agreed on its essential elements, even if certain matters remain unresolved. A court or tribunal may potentially fill in the gaps by considering what the parties had in mind.
Referring to the new UAE Civil Transactions Law, which came into effect in June, he highlighted Article 121, which requires parties to act in good faith when proposing, conducting and ending negotiations. A party may therefore face liability where it engages in negotiations in bad faith, including keeping the other party engaged to obtain information despite having no genuine intention of concluding the transaction. The damages would ordinarily reflect the actual loss incurred, although parties may agree to provide for loss of profits. He cautioned that parties should specifically identify the essential elements that must be agreed upon before a binding contract can arise. Merely describing a document as “non-binding” or “subject to contract” may not be sufficient under the onshore UAE framework.
On disclosure, Mr. Randeniya referred to Article 122, which requires parties to disclose information of decisive importance to the other party’s consent. He also referred to circumstances where the other party’s ignorance is presumed or where it has placed trust in the counterparty. He noted that the scope of this obligation remains to be tested, given the recent introduction of the provision and the limited guidance currently available. He observed that the duty cannot be limited or waived by contract and that courts or tribunals may disregard contractual provisions seeking to exclude it.
He also highlighted the newly recognised duty not to misuse or abuse information received during negotiations. A party seeking damages for breach would still need to establish the relevant disclosure, loss and actual damage suffered. He clarified that although this duty had been newly recognised under the onshore framework, the concept was not new under the other framework he referred to during the discussion.
Purchase price adjustments and earn-out disputes
Turning to disputes arising after completion, Ivana Dahl outlined the principal mechanisms used to determine purchase price. These include a locked-box arrangement, under which the price is fixed by reference to an agreed date, and completion accounts, under which the parties make an initial estimate of the business’s value and subsequently adjust the price based on its actual financial position at completion.
She observed that disputes over purchase price adjustments generally concern accounting questions, including whether an item should be classified as debt or working capital, whether an amount has been double-counted and which accounting principles should apply. She clarified that she had not seen many such disputes arise in practice, whereas earn-out mechanisms had generated more disputes.
Ms. Dahl noted that earn-out mechanisms have generated more disputes. Under these arrangements, part of the purchase price is dependent on the business achieving specified targets after completion. Disagreements can arise where the seller believes that the buyer’s management decisions, changes in customers or alterations to the business have affected its ability to achieve those targets. While buyers generally seek the flexibility to operate the acquired business, sellers may seek contractual protections to ensure that the buyer’s decisions do not undermine their entitlement to additional consideration.
She emphasised the importance of clearly defining financial terms, setting out worked examples of how calculations are to be undertaken and specifying the accounting principles and their order of priority. Parties should also address information-sharing obligations and access and audit rights.
From a dispute resolution perspective, Ms. Dahl stressed that the dispute resolution clauses across the sale and purchase agreement, shareholders’ agreement and other transaction documents should be aligned. This is particularly important where accounting questions may require expert determination, while contractual or legal issues may need to be decided by an arbitrator. The contract should also address how overlapping issues will be managed.
She added that due diligence remained a key priority for ADNOC’s international investments through XRG, an independent investment company established in 2024. In her view, spending more time on due diligence at the outset can help identify potential issues before they develop into disputes.
Warranty claims and the role of W&I insurance
Sami Tannous examined the claims that may arise when representations and warranties in a sale and purchase agreement are found to be inaccurate or breached after completion.
He explained that warranty claims can concern misleading financial statements, interim operating covenants and actual or threatened litigation. In particular, disputes may arise during the period between signing and closing, when the seller is required to operate the business in accordance with its past practices.
Mr. Tannous cautioned that establishing a warranty breach does not automatically establish a compensable loss. He emphasised the distinction between value and price, explaining that the measure of loss for a warranty claim involves comparing the value of the company as warranted with its value in the condition in which it was received. The price paid may be an indicator of value, but it is not necessarily conclusive.
He illustrated that a breach may exist without resulting in actual loss where the buyer has already overpaid for the business. Conversely, where the business is valued using an EBITDA multiple, a relatively small underlying loss may have a significantly greater effect on the company’s value.
He also emphasised the importance of independent accounting and valuation expertise when assessing warranty claims. Relying solely on the client’s own accountants may not provide an independent assessment of the merits, potentially leading to unexpected difficulties during arbitration.
On warranty and indemnity insurance, Mr.Tannous explained that buy-side W&I insurance changes the route through which a buyer pursues a claim, rather than removing the need to establish a breach. The seller’s liability under the sale and purchase agreement is often reduced, subject to specified exceptions, while the buyer seeks recovery from the insurer.
The buyer must therefore establish both that a warranty was breached and that the breach falls within the scope of the insurance policy. Complications may arise where the buyer requires the seller’s assistance in pursuing an insurance claim, particularly if the sale and purchase agreement and the insurance policy contain different dispute resolution arrangements.
Valuation evidence, loss and restrictive covenants
Montek Mayal observed that disagreements over valuation at the time of a transaction can subsequently develop into disputes over price. He emphasised that disputes over valuation frequently concern not only the calculation of value but also the conduct and obligations of the parties after completion. In particular, sellers may argue that changes in the buyer’s business plans or management decisions have affected the performance of the acquired business.
He stressed the importance of documenting the process through which the buyer and seller arrived at the transaction value, including the role of advisers and the valuation evidence considered. Such records can become important when establishing causation and assessing loss.
Mr. Mayal distinguished between losses that can be measured on a dollar-for-dollar basis, such as an understatement of debt, and recurring losses that affect the business’s performance and valuation. Where a misrepresentation concerns a material contract or the business’s performance trajectory, the impact may extend beyond a single financial item and affect the valuation of the business as a whole.
He also discussed the importance of protecting goodwill, customer relationships and information held by founders and promoters. From the buyer’s perspective, non-compete and non-solicit obligations can serve as contractual protections against the founder or promoter establishing a competing business or soliciting customers and employees.
He explained that non-compete obligations may prevent a founder or promoter, and in some cases their family members or affiliates, from establishing or participating in a competing business within a specified territory, period or sector. Non-solicit obligations, on the other hand, prevent the founder from actively soliciting customers or employees to move with them.
However, he cautioned that the enforceability of non-compete provisions differs across jurisdictions. In India, such provisions are generally treated as restraints of trade, with exceptions including restrictions during the term of employment and certain restrictions accompanying the sale of goodwill. He observed that the sale-of-goodwill exception requires an actual valuation and cannot be addressed merely by inserting a reference to goodwill in the agreement.
By contrast, he noted that non-compete obligations are more readily enforceable in the UK, Singapore and the UAE, provided they are reasonable.
Mr. Mayal also suggested that parties consider commercial protections such as holdbacks, deferred consideration and liquidated damages, rather than relying exclusively on court proceedings and injunctions. He referred to the possibility of protecting confidential information through confidentiality obligations, which may provide an alternative basis for seeking injunctive relief.
Confidentiality and protection of sensitive information
The discussion then turned to the protection of information shared during negotiations and the consequences of its misuse.
Ivana Dahl explained that confidentiality obligations should be addressed at every stage of a transaction and not treated as a provision that is included in an agreement and then overlooked. She referred to the practice of requiring a separate non-disclosure agreement before entering into settlement discussions after a dispute has arisen, particularly where the parties wish to prevent communications and documents exchanged during negotiations from being used in subsequent proceedings.
She observed that a general confidentiality clause in an existing project agreement may not adequately cover the specific purpose and circumstances of later settlement discussions.
Ms. Dahl also discussed the practical steps taken by in-house counsel to preserve the confidentiality of legal advice. These include keeping legal advice in separate emails or documents rather than combining it with ordinary business communications, and clearly identifying legal communications as confidential.
In the context of joint ventures, she highlighted the risk that a co-founder may also be involved in another business operating in the same market or dealing with the same customers. Confidentiality clauses should therefore address not only the disclosure of confidential information but also its use for the individual’s own interests.
Where confidential information has been misused, Ms. Dahl identified interim injunctions as particularly important to prevent further dissemination. Damages may also be available, although quantifying the resulting loss can be difficult.
Investor exits and shareholder transfer disputes
Sami Tannous discussed the exit mechanisms commonly found in private equity transactions, where investors typically operate with an investment horizon of five to seven years.
He identified drag-along rights as a potential source of disputes. These rights may allow an investor who has found a buyer for its stake to require other shareholders to sell their shares as part of the transaction. Disagreement may arise where the other shareholders are dissatisfied with the proposed sale price.
Put options can also generate disputes, particularly where an investor seeks to require the remaining shareholders to purchase its shares at a predetermined price, often calculated using an internal rate of return-based mechanism. Other potential sources of disagreement include call options and IPO-related exit mechanisms, where parties may dispute whether the necessary steps towards an IPO have been taken.
Mr. Tannous observed that these mechanisms are particularly relevant in the Middle East, where private equity investors have increasingly invested in large family-owned businesses and conglomerates. He noted that investment agreements may provide for assured returns and, depending on the agreed mechanism, the exit price may increase the longer the investor remains invested.
He also explained why disputes over exit arrangements do not always proceed to formal proceedings. Uncertainty surrounding enforcement, particularly in relation to onshore mechanisms in the UAE, may influence the parties’ approach and encourage commercial negotiations. The relatively short investment horizon of private equity investors also makes lengthy litigation and enforcement proceedings less attractive. He observed that disputes may begin contentiously but ultimately be resolved through commercial negotiations.
Khushboo Shahdadpuri then addressed disputes concerning rights of first refusal, tag-along rights and restrictions on share transfers. She observed that corporate structures in the UAE do not provide the same range of statutory remedies for these mechanisms as some other jurisdictions.
In her experience, disputes concerning rights of first refusal are more common than those involving tag-along rights and lock-in provisions. She referred to statistics suggesting that 80% of businesses in the MENA region are family-run or family-owned and that 60% of the region’s wealth is generated by these businesses. Against this background, she explained that a recurring issue in family-owned businesses is whether a transfer to a family trust or another related family business qualifies as a permitted transfer or triggers pre-emption rights.
She also highlighted disputes concerning valuation mechanisms, including whether the contractual formula remains suitable in the circumstances prevailing at the time of the transfer. External factors, including adverse weather conditions affecting oil terminals or coal mining sites, may influence the value of the relevant business or assets.
Other areas of disagreement include discounts, double recovery and non-cash consideration, particularly whether an asset or share transfer represents the appropriate value. Ms. Shahdadpuri further noted that disputes may arise over notice requirements, including the period of notice, the information required to be included and whether the contractual preconditions for exercising a particular right have been satisfied.
She observed that even where contracts contain extensive provisions, disputes frequently arise over basic requirements, including whether a notice provision has been triggered and whether the required information has been provided.
Reflective loss and derivative actions
In the final substantive exchange, Chatura Randeniya examined the distinction between losses suffered by a company and losses suffered by its shareholders, particularly where the same set of facts may give rise to multiple claims.
He explained that the reflective loss principle prevents a shareholder from personally claiming for a reduction in the value of shares or distributions where that loss merely reflects loss suffered by the company, and the company itself has a cause of action against the alleged wrongdoer. The principle ensures that compensation is paid to the party that actually suffered the loss and prevents multiple recoveries for the same harm.
Mr. Randeniya observed that the issue can become particularly complex in M&A transactions involving multiple shareholders, investment vehicles and subsidiaries, where the same facts may give rise to claims under the sale and purchase agreement and other legal instruments.
He identified two important considerations for tribunals: determining the event that gave rise to the loss and identifying the party entitled to claim it; and establishing the applicable law. She noted that the position may differ between free-zone and onshore regimes and that the reflective loss principle does not operate as an absolute prohibition on shareholder claims. A shareholder who has independently suffered loss, for instance through misrepresentation, may still have a personal claim.
He also discussed derivative actions, through which shareholders may bring proceedings in their own name as well as on behalf of the company. Referring to differences in the applicable thresholds across regimes, he highlighted that the availability and requirements of such actions depend on the governing legal framework. He referred to the absence of a statutory minimum threshold under one regime, a 10% threshold under the onshore regime and a 5% threshold under another regime. He also raised the question of whether a common law derivative action continues to survive under the relevant company regulations.
Finally, Mr. Randeniya cautioned that reflective loss issues may emerge only after proceedings have commenced, including following a change of counsel. Where such an issue is raised during arbitration, tribunals must ensure that it is properly considered and that all parties have an opportunity to present their case. Failure to provide such an opportunity may expose the relevant part of an award to challenge.
Conclusion
The discussion highlighted that post-M&A disputes can arise at every stage of a transaction, from preliminary negotiations and disclosure obligations to valuation disagreements, warranty claims, confidentiality breaches and investor exits.
The panellists repeatedly emphasised the importance of clear contractual drafting, carefully defined financial mechanisms, adequate information and audit rights, and appropriate dispute resolution provisions. They also highlighted the need for independent valuation and accounting evidence when assessing claims and establishing loss.
Ultimately, the discussion underscored that investor protection does not depend on a single contractual safeguard. It requires parties to anticipate how commercial relationships may evolve after completion and to structure their agreements, remedies and exit arrangements accordingly.
SCC Times is the Official Information & Documentation Partner for Dubai Arbitration Week 2026. Stay tuned for comprehensive coverage, key insights and highlights from the event!