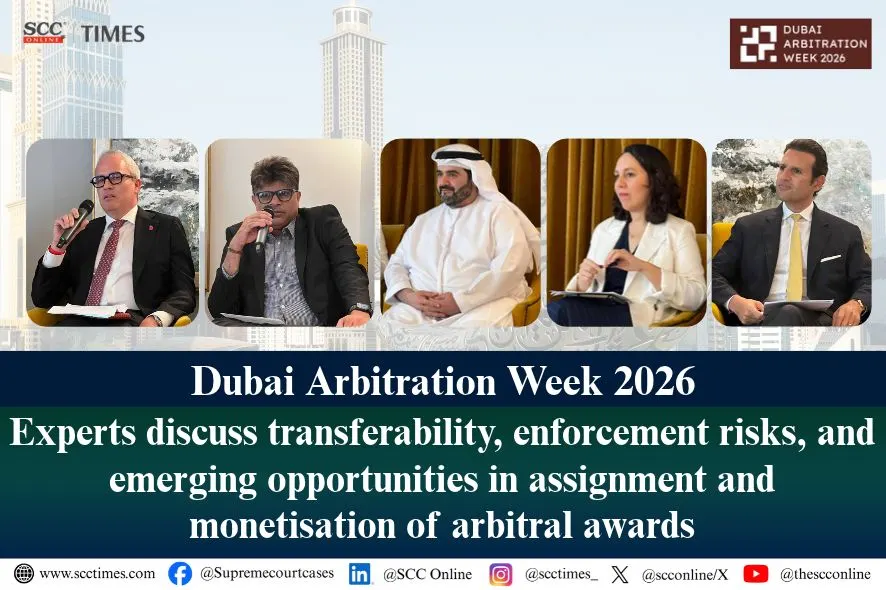
Organised by the Dubai International Arbitration Centre (DIAC), the Dubai Arbitration Week 2026, being held from 9 to 13 November 2026, brings together the global arbitration community for a week of panel discussions, workshops and networking, highlighting Dubai’s growing role as an international dispute resolution hub and providing a platform to exchange perspectives on emerging trends, innovations and the future of arbitration.
In a panel discussion, organized by JSA Advocates & Solicitors, titled “Awards as Assets: Assignment, Financing and Monetisation of Arbitral Awards Across Borders”, the panellists examined the growing significance of the assignment and monetisation of arbitral awards, with particular focus on the distinction between third-party funding of claims and the purchase of awards, the commercial considerations involved in valuing an award, and the legal and practical challenges associated with enforcement across jurisdictions. The speakers discussed the role of funders and legal practitioners in assessing recovery prospects, the importance of identifying assets at an early stage, the transferability of arbitral awards under different legal frameworks, and the particular challenges arising in cases involving sovereign debtors.
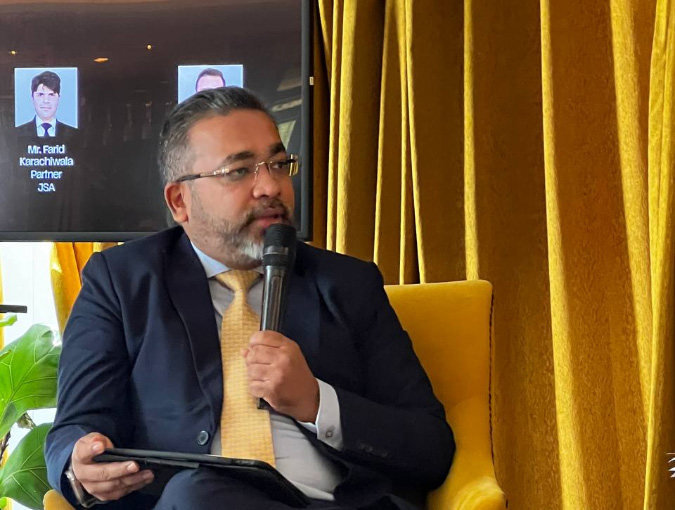
Moderated by Mr. Divyam Agarwal, Partner, JSA, the panel consisted of esteemed legal professionals, namely, Mr. Abdulla Galadari, Senior Partner, Galadari: Advocates and Legal Consultants; Mr. Jonathan Huth, Partner, Charles Russell Speechlys; Mr. Ziad Obeid, Partner, Obeid & Partners; Ms. Sumru Akter, Investment Manager, Senior Legal Counsel, Omni Bridgeway; and Mr. Farid Karachiwala, Partner, JSA.
Opening the discussion, Mr. Divyam Agarwal observed that lawyers often inform clients that they have won an arbitration, only for clients to ask when they would actually receive the money. He described the discussion as focusing on the gap between obtaining an award and recovering the amount awarded. Introducing the subject, he referred to the historical treatment of funding another person’s litigation in England and the evolution of litigation funding into an asset class. He asked whether purchasing an arbitral award was fundamentally different from funding a claim or merely represented the same business at a later stage.
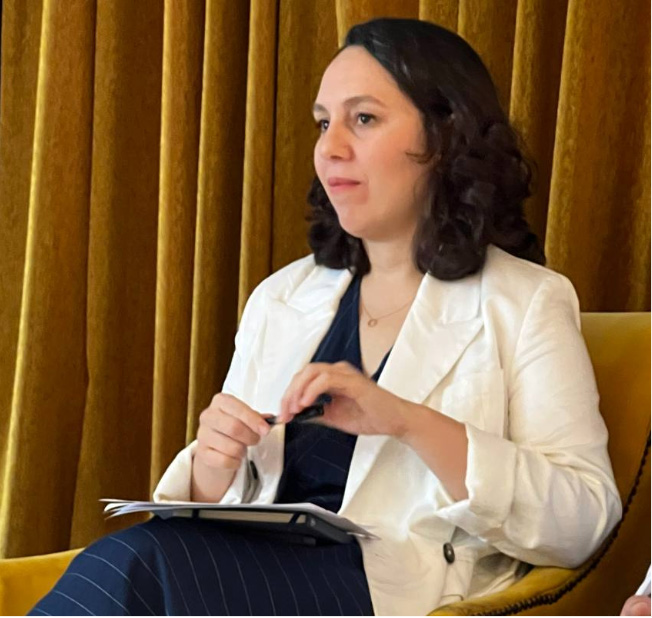
Difference award monetisation and litigation funding: Ms. Sumru Akter
Responding to the question, Ms. Sumru Akter explained that, from a commercial perspective, the client’s primary concern was often the actual recovery of money rather than merely succeeding on the merits of a dispute. She said that the monetisation of awards was an important mechanism through which a client could generate liquidity.
Distinguishing award monetisation from claim funding, she explained that a funder financing an arbitration or litigation assumed the merits risk and the risks associated with the proceedings themselves. In contrast, where an award has already been issued, the merit-based risk has substantially matured. The principal concern in such a transaction is the recovery risk rather than the merits of the underlying dispute.
She explained that this distinction also affected the due diligence undertaken by a funder. The assessment would focus on the proposed enforcement strategy, the jurisdictions in which the debtor’s assets were located, the anticipated cost and duration of enforcement, and the possibility of competing creditors. Where the debtor was a State, the funder would also have to consider sovereign immunity and restrictions on the attachment of assets.
Ms. Akter further underscored that the nature of the relationship between the creditor and the funder depended on the structure of the transaction. In an outright purchase of an award, the buyer steps into the shoes of the creditor, who would no longer remain the party pursuing recovery. In a conventional funding arrangement, however, the claimant continues to hold the claim and remained a party to the dispute, while the funder financed the costs and had limited scope to interfere with the litigation strategy.
Thus, she concluded that claim funding means investing in the outcome of litigation, whereas award purchase/ monetisation involved investing in the ability to convert an existing legal entitlement into money.
UAE market on funding and award assignments: Mr. Abdulla Galadari
Answering whether businesses in the UAE were actively using award monetisation or whether the market remained concentrated in established centres such as London and New York, Mr. Abdulla Galadari stated that the market was still primarily concentrated in London and New York, although changes were beginning to emerge in the UAE. He emphasised the importance of understanding the commercial culture and how legal frameworks evolved in response to developments in the business community.
Referring to the development of private credit in the UAE, he observed that funding entered the UAE market relatively late and a decade earlier, it was difficult to reach an understanding on funding a claim. However, the regulatory frameworks of the Abu Dhabi Global Market (ADGM) and the Dubai International Financial Centre (DIFC) had made claim funding more accessible and practical. However, he differentiated this development from the assignment of an award, explaining that transferring an existing creditor’s position involved a different set of considerations.
To illustrate how commercial culture could influence legal development, Mr. Galadari referred to the evolution of compensation practices in medical negligence cases in Dubai. He explained that compensation for serious injuries had historically been limited compared with practices in Western jurisdictions. However, engagement between the business community, lawyers, medical professionals, hospitals, the Dubai Health Authority, and the courts had contributed to a change in the approach. He observed that the development of medical tourism had also highlighted the need for an effective compensation framework. Over time, the courts began awarding substantially higher compensation, including amounts running into tens of millions.
Thus, he drew a parallel with the developing market for assignment and monetisation of arbitral awards, noting that legislative changes were responding to the evolving requirements of the business community.
Factors which determine an award’s value: Ms. Sumru Akter
Continuing the discussion, Ms. Akter explained a few factors that made an arbitral award commercially attractive to a prospective purchaser:
-
Clear and enforceable: The language of the award and the orders contained in it had to be unambiguous. She cautioned that an award could lose considerable value if the limitation period for enforcement had already expired in the jurisdictions where the debtor’s assets were located. Accordingly, the applicable limitation period had to be assessed considering the location of the assets and the relevant enforcement jurisdiction.
-
Finality: She further explained that a prospective purchaser would examine whether the award was final and whether there remained any risk of setting aside or annulment proceedings. The duration of any pending challenge would also affect the commercial assessment.
-
Treatment of interest: Since a funder assumed the risk of potentially lengthy recovery proceedings, the continued accrual of interest was a significant component of the economic viability assessment. However, Ms. Akter observed that she had encountered several awards wherein interest had either not been properly argued or had been overlooked altogether. This could benefit the debtor by enabling it to delay payment while limiting the creditor’s eventual recovery.
-
Location and nature of the debtor’s assets: The purchaser would assess whether the assets were situated in enforcement-friendly jurisdictions, whether immunity issues could arise, and whether the debtor had the financial capacity to satisfy the award. It was also necessary to understand whether non-payment resulted from an inability to pay or from deliberate litigation tactics intended to delay recovery.
Ms. Akter explained that these factors influenced the price offered for an award. A funder had to assess the initial investment, the likely recovery period and the legal budget required for enforcement. The longer the recovery process, the more expensive the investment became. As fund managers were also accountable to investors and had return-on-investment obligations, those considerations had to be reflected in the valuation. She emphasised that purchasers do not acquire awards at their face value rather they assess the amount that could realistically be recovered and structured their financing accordingly.
On the question of timing, she explained that the duration of recovery was critical to the funder’s return. In award monetisation, the investment is generally made upfront, unlike arbitration funding, where expenditure is spread over the course of the proceedings. Consequently, even a delay of a few years could significantly affect the expected return. The appropriate recovery period, however, depended on the jurisdiction and the circumstances of the award.
Red flags that could kill an award purchase deal: Mr. Farid Karachiwala
Regarding the red flags that could lead a prospective buyer to decline an award, Mr. Farid Karachiwala identified a few considerations:
-
Risk of the award being set aside: He explained that the legal assessment means whether the arbitration process had been completed in the way that it was contemplated. This would include whether the arbitration agreement had been signed by the relevant party, whether that party had participated in the arbitration, and whether it had participated in the constitution and appointment of the tribunal. The buyer’s lawyer would also examine whether the tribunal had acted within its jurisdiction or exceeded the authority conferred upon it, which would be susceptible to challenge.
-
Enforcement Hurdles: In this assessment, the lawyer must check the availability of effective enforcement remedies. They would examine the jurisdiction in which enforcement was proposed and assess whether its courts were generally receptive to enforcement proceedings. He also highlighted the possibility that a jurisdiction might resist enforcement of awards against local companies on public policy grounds.
-
Allegations against arbitrator(s): The buyer would investigate any allegations concerning the tribunal or the arbitrator, including allegations of fraud, witness tampering or bribery. Such allegations could provide grounds for challenging the award and therefore had to be examined during due diligence.
-
Pending Appeals: This meant assessment of whether an appeal or an application for setting aside the award was pending. The buyer would need to understand the nature and merits of the proceedings and the extent to which they could affect enforcement.
-
Contractual Protections: Lastly, Mr. Karachiwala emphasised the importance of contractual protections in the assignment agreement. The seller should be willing to provide appropriate representations, warranties, and indemnities concerning the award and the financial position or insolvency of the debtor company. Reluctance to provide customary contractual assurances would be a significant warning sign and could lead the buyer to reconsider the transaction.
Enforcement hurdles and seller’s perspective: Mr. Jonathan Huth
Addressing the position of sellers, Mr. Jonathan Huth argued that lawyers often approached arbitration and enforcement as separate stages, although the actual success of a dispute depended on recovering the money rather than merely obtaining an award.
He suggested reversing the conventional approach by focusing on the assets before focusing on the award. Drawing an analogy with an investment in a company, he explained that a seller should understand the value of the asset being sold before approaching a potential purchaser. Just as a company would undertake its own due diligence before allowing an investor to assess its value, an award holder should prepare the necessary information before entering the market.
Mr. Huth underscored the tendency to separate arbitration lawyers from enforcement lawyers, observing that the latter were frequently not involved until the award had already been issued. This could leave the claimant without a clear understanding of the assets available for enforcement, the relevant jurisdictions or the considerations that a prospective purchaser would examine.
He explained that involving enforcement lawyers at the beginning would enable the claimant to identify assets and assess enforcement options while the arbitration was still underway. Illustrating his point with an anecdote, he mentioned a case that he was working on, wherein enforcement strategies had been budgeted from the beginning, allowing the legal team to consider potential pressure points even during the arbitration.
Considering enforcement at the outset, he explained, meant the involvement investigation and intelligence firms. They would aid in identifying relevant jurisdictions and budgeting for the costs and complexity of enforcement. This preparation would assist the claimant not only in pursuing recovery but also in determining the commercial value of the award if it later decided to sell it.
Mr. Huth observed that sellers sometimes walked away from enforcement because they were unable to assess the value of their awards or had become exhausted after years of litigation. He described litigation fatigue due to the failure to prepare clients for the recovery stage. After spending substantial amounts on arbitration, clients could find themselves holding an award without understanding how much it was worth or how it could be enforced.
He also encouraged lawyers to adopt a commercial and creative approach when working with funders. Referring to funding arrangements within his firm, he explained that the firm could assume certain risks associated with the case and even insure its own work in progress. Where a client could not afford the insurance premium, the cost could be incorporated into the funding arrangement. Such structures could reduce the overall risk for a funder and make the transaction more attractive.
He cautioned against approaching the funding market with an inadequately prepared case. If an award or claim was circulated among funders without proper due diligence, a subsequent attempt to approach the market with a better-prepared proposal could be unsuccessful because prospective funders might already have declined the opportunity.
Thus, Mr. Huth concluded that sellers should be informed about the value of their awards and the available enforcement strategies from an early stage. He urged lawyers to involve enforcement practitioners from day one, and, where the necessary expertise was unavailable within their own firms, to collaborate with other firms and specialist investigation and intelligence agencies.
Timing to sell an award: Mr. Ziad Obeid
Mr. Ziad Obeid began by identifying three propositions relevant to the monetisation of arbitral awards.
-
First, he explained that an award was not money but a legal entitlement to money. The difference between obtaining that entitlement and recovering the amount was what a purchaser was seeking to value.
-
Secondly, he agreed that monetisation should be considered well before the award was issued. If enforcement was considered only after the award had been rendered, the creditor might already have lost important opportunities to identify assets or secure recovery.
-
Thirdly, he distinguished between the legal transferability of an award and its commercial value. An award might be legally assignable but extremely difficult to enforce. Conversely, an award that presented enforcement difficulties could still have considerable settlement value.
Answering the question of when a creditor should sell an award, Mr. Obeid suggested that the first question should be why the creditor wished to sell it rather than when. A company might require immediate liquidity or might simply wish to end years of litigation and avoid further expenditure on complicated enforcement proceedings.
He illustrated this through the example of a 100-million-dollar award against a solvent debtor with identifiable assets in an enforcement-friendly jurisdiction. If the creditor was reasonably confident of recovering the amount within six months or a year, selling the award at a substantial discount might not be commercially sensible unless the creditor urgently needed liquidity. The position would be different where enforcement was difficult, assets were difficult to locate and legal costs continued to increase. In such circumstances, selling the award could become more attractive to the creditor, although the same difficulties would make the award less attractive to a prospective purchaser.
Mr. Obeid connected this problem with the economic concept of adverse selection, referring to economist George Akerlof’s work on the market for used cars1. In that context, the seller generally possessed more information about the quality of the vehicle than the buyer. The buyer, aware of this information imbalance, discounted the price, which could discourage sellers of higher-quality vehicles from entering the market. He drew a parallel with award monetisation, explaining that the creditor often knew more about the debtor’s conduct, financial position and recovery prospects than the purchaser. A prospective buyer could therefore question why the creditor was willing to sell an apparently valuable award.
Agreeing with Mr. Huth, Mr. Obeid reiterated the importance of involving enforcement lawyers at the beginning of the dispute. He also highlighted the need to examine the financial position of the contracting party, whether it was a well-capitalised company or a special purpose vehicle, and whether there might be a basis for extending the arbitration agreement to third parties. Other considerations, including sanctions and potential enforcement obstacles, also had to be examined before commencing arbitration. He cautioned that a party could spend several years and substantial sums pursuing arbitration only to obtain an award that was difficult to convert into tangible recovery.
Regarding the appropriate time for sale, he stated that there was no universal answer. Immediately after the award was issued, uncertainty concerning the merits would have reduced, but the prospects of recovery would remain untested. Commencing asset tracing or preliminary enforcement proceedings could provide greater clarity, although the information obtained might also reveal difficulties that affected the price. As time passed, the creditor could find it increasingly difficult to secure a buyer, and the buyer might demand a larger discount.
Mr. Obeid also highlighted the importance of interim measures, including those available before local courts. In certain jurisdictions, provisional seizures could be obtained while the arbitration was still pending. Such measures required the early identification of assets and could help prevent their dissipation before enforcement became necessary.
He noted that some jurisdictions permitted provisional seizure where the likelihood of the existence of the debt was established, without necessarily requiring proof of a risk of asset dissipation. He suggested that parties should consider such remedies at the beginning of the dispute rather than waiting until the award had been issued.
Contractual non-assignment clauses do not necessarily prevent assignment of an arbitral award: Mr. Farid Karachiwala
The discussion then turned to whether anti-assignment clauses commonly found in commercial contracts could prevent the subsequent assignment of an arbitral award.
Mr. Karachiwala explained that a distinction had to be drawn between restrictions on the assignment of contractual rights and the assignment of rights that had culminated into an award. A non-assignment clause in a contract generally concerned contractual performance, obligations, and the transfer of unresolved rights. Once those rights culminated in an arbitral award, the contractual position changed.
Referring to Indian law, he stated that a domestic arbitral award was treated as a decree under Section 36 of the Arbitration and Conciliation Act, 1996 (the Arbitration Act). He explained that a decree or judgment of a court could be assigned and that the existence of a non-assignment clause in the underlying contract did not, by itself, necessarily prevent the assignment of the benefits of an award.
He emphasised two practical requirements for an assignment in India:
-
Written Document: The assignment should be affected through a written instrument or deed of assignment.
-
Stamp Law: The relevant stamp law had to be considered, since each State had its own stamp law and the applicable stamp duty shall to be paid.
He added that although an assignment could be valid, its practical operation might be affected by pending proceedings challenging the award. Where a challenge had been filed, the consequences would depend on the decision of the court hearing that challenge. Nevertheless, he maintained that a contractual non-assignment clause did not automatically bar the assignment of an award.
UAE on assignment of rights: Mr. Abdulla Galadari
Mr. Agarwal next asked Mr. Galadari whether an assignee seeking enforcement of a New York Convention award before a Dubai court would simply step into the shoes of the original creditor.
Mr. Galadari referred to recent legislative developments in the UAE whereby such an award could be enforced. He also referred to judicial developments concerning compound interest, stating that the relevant appellate and cassation decisions had recognised that compound interest was not contrary to public policy. He observed that enforcement of arbitral awards in the UAE had become more favourable over the last 10-15 years. Earlier difficulties had created concerns for institutional and foreign investors, but the legal framework had gradually developed in a more enforcement-friendly direction.
Regarding assignment, he referred to Articles 405 to 417 of the Civil Transactions Law2 and stated that, following the legislative changes effective from June 2026, the debtor’s consent was no longer required for an assignment of rights.
Mr. Galadari viewed these developments as part of the UAE’s broader effort to create a business-friendly legal environment. He also described arbitral awards as a potentially attractive asset class for institutional investors, given the possibility of purchasing an award at a discount and generating a return if the amount recovered exceeded the purchase price.
He opined that courts were becoming more receptive to such transactions and anticipated further legislative developments to make the process more seamless.
Assignment of commercial awards in UK and DIFC: Mr. Jonathan Huth
From the perspective of an enforcement lawyer, Mr. Huth examined the position under the DIFC and English legal frameworks, distinguishing between commercial arbitral awards and awards arising under international investment treaties.
With respect to commercial awards, he explained that assignment was not expressly prohibited or expressly permitted under the DIFC Arbitration Law. He referred to Section 42, which provides for recognition of arbitral awards irrespective of the State or jurisdiction in which they were made, subject to the relevant statutory provisions. He also referred to Section 43, which addresses the recognition of an arbitral award by the DIFC Courts.
Considering these provisions alongside the broader approach of the DIFC towards common law principles and the legislative developments discussed by Mr. Galadari, Mr. Huth suggested that there was a basis for an assignee to seek recognition and enforcement of a commercial award.
Turning to England, he explained that the legal wording was somewhat narrower. The English Arbitration Act, 1996, provides for recognition of New York Convention awards as binding on the persons between whom they were made, while the Section 136 of the Law of Property Act, 1925, contains requirements concerning assignment, namely, absolute assignment in writing and express written notice to the debtor.
He referred to the decision in OperaFund Eco-Invest SICAV PLC & Anor v Kingdom of Spain3, wherein it was observed that the assignability of commercial arbitral awards had received limited judicial attention, while indicating a broader consensus that an assignee could seek enforcement. Thus, for commercial awards, the DIFC referred to the UK law, its own laws, and precedents.
However, Mr. Huth cautioned that a different position could arise in relation to investment treaty awards. Referring to the recent appeal filed by Blasket Renewable Investments LLC in OperaFund (supra), he stated that the English Court of Appeal had affirmed that ICSID awards could not be assigned without the consent of the debtor State. This created a divergence between the English position and approaches in jurisdictions such as the United States, Australia, and the Netherlands.
Thus, Mr. Huth stated that his advice to clients in relation to investment treaty awards was to avoid assignment, given the legal uncertainty.
Cross-border transferability and monetisation of arbitral awards: Mr. Ziad Obeid
Mr. Obeid agreed that the recent English developments raised important questions concerning the transferability of investment treaty awards. He noted that though an appeal had been filed before the UK Supreme Court in OperaFund (supra), it was a relevant decision concerning ICSID awards. He distinguished these awards from non-ICSID investment treaty awards rendered with national seats, which could be enforced under the New York Convention. Additionally, the New York Convention does not prevent assignees from enforcing qualifying awards.
He suggested that the market might need to reconsider how award monetisation transactions were structured. If outright assignment could not be assumed to be universally available, funders and creditors might move away from straightforward purchases in which the funder stepped into the creditor’s shoes. Instead, they could consider economic participation structures, funded arrangements and irrevocable beneficial ownership arrangements, under which the original creditor continued to pursue enforcement in its own name.
Turning to the UAE, he referred to the distinction between the ADGM and DIFC courts and the local onshore courts. He discussed the recent codification of provisions concerning the transfer of rights under the UAE Civil Code, particularly the concept of Hawalat al-Haq (transfer of a legal right). He explained that the transfer of a right could take effect between the parties upon execution of the transfer, while notification was necessary to make it enforceable against third parties. The debtor’s consent was not required. He observed that the UAE’s increasingly pro-enforcement approach could support assignment before the onshore courts. However, questions could arise before the ADGM and DIFC courts because of their consideration of English Court of Appeal judgments.
Mr. Obeid also drew attention to Article 1699 of the French Civil Code, which provides for the mechanism of retrait litigieux. Under this mechanism, in certain circumstances, a debtor may extinguish a disputed right that has been sold by reimbursing the purchaser for the price paid to acquire it, together with the relevant interest. He explained that the provision was intended, among other things, to prevent speculation in disputed claims. Thus, he suggested that funders should consider the implications of this provision when assessing transactions involving French law.
Enforcement possibilities across jurisdictions and financing enforcement: Ms. Sumru Akter
Ms. Akter agreed that the validity and commercial attractiveness of an assignment had to be examined considering the jurisdiction in which enforcement was intended. She explained that a restriction on assignment or enforcement in one jurisdiction did not necessarily mean that the award could not be monetised elsewhere. Referring to Slowakische Republik (Slovak Republic) v. Achmea BV4, and Republic of Moldova v. Komstroy LLC5, she observed that a debtor might successfully resist enforcement in a European jurisdiction but face a different outcome in the United States, where the courts might not recognise the same restrictions arising under EU legislation.
She also referred to developments in France, including a case involving Cameroon6 in which a funder enforced an assignment under a pledge following a breach of a litigation funding agreement. The courts upheld the pledge and the funding agreement, permitting the funder to enforce the judgment in its own name.
Ms. Akter emphasised that outright purchase of an award was not the only product available to funders. Where assignment was legally unavailable or commercially undesirable, a funder could finance the enforcement proceedings while allowing the original creditor to remain the claim holder. Such financing could cover not only legal costs but also an upfront working-capital payment to support the creditor during enforcement. She also referred to award preservation or default insurance, under which a funder could pay the insurance premium and provide support against the risk of the debtor failing to satisfy the award. These arrangements could provide financial support without requiring an assignment and could therefore avoid the legal risks associated with transferring the award.
Multiple jurisdictions create additional enforcement opportunities: Mr. Jonathan Huth
Continuing the discussion, Mr. Agarwal asked Mr. Huth whether an award involving assets in several countries was more attractive to a purchaser or merely increased the complexity and cost of enforcement. Mr. Huth responded that the presence of assets in multiple jurisdictions could create additional opportunities to apply pressure on the debtor and encourage settlement. The relevant considerations included the legal risks in each jurisdiction, the identity of the individuals or entities behind the assets, and whether the assets included businesses, real estate or other property.
He stated that the involvement of several jurisdictions could increase the cost of enforcement but did not necessarily make the award less attractive. If the assets and the relevant corporate or individual networks were identified early, the creditor could use different enforcement avenues to increase the value of the claim.
Mr. Huth reiterated that early investigation and asset tracing were essential. By understanding the debtor’s asset structure and identifying potential pressure points, lawyers could improve the prospects of recovery and enhance the commercial value of the award.
Are Sovereign harder to sell? : Mr. Ziad Obeid
Regarding the challenges associated with awards against sovereign States and State-owned entities, Mr. Obeid explained that the commercial value of an award against a State depended significantly on the identity and circumstances of the State concerned. An award against a stable State with substantial assets, international commercial activities, and a reputation to protect presented a different risk profile from an award against a State affected by sanctions, armed conflict, or institutional instability.
He identified sovereign immunity as a central consideration. A distinction had to be drawn between immunity from jurisdiction and immunity from execution. Although a State could potentially be subjected to arbitration proceedings, the ability to execute an award against its assets would depend on the applicable law in the relevant jurisdiction.
He further highlighted the need to determine whether a State-owned entity was legally independent or constituted an emanation of the State. This required close examination of the entity’s constitutional documents and its separate legal personality. In certain situations, the difficulty could be compounded by uncertainty over which authority legitimately represented the State. Referring to circumstances involving Libya and Yemen, he explained that competing factions could claim to represent the government, creating uncertainty about who could issue instructions and who would ultimately satisfy the award.
Mr. Obeid also distinguished between a State’s ability to pay and its willingness to pay. Unlike a corporate debtor, a sovereign State could not simply be placed into liquidation by its creditors. However, a State might be incentivised to satisfy an award to preserve access to international financing, maintain relationships with institutions such as the World Bank, protect important commercial relationships or avoid disruption to significant transactions.
He explained that these considerations could create leverage for creditors beyond the immediate prospect of attaching State property. Accordingly, the commercial assessment of a sovereign award had to consider not only the State’s financial capacity but also the incentives that might encourage it to pay.
Award monetisation as relief to creditors facing litigation fatigue
Mr. Galadari observed that award monetisation could provide relief to creditors who possessed enforceable rights but lacked the resources or ability to pursue lengthy recovery proceedings. He agreed with Mr. Huth’s statement that litigation fatigue could lead creditors to abandon enforcement despite having obtained an award. The involvement of professional purchasers and funders could provide a fresh opportunity to pursue recovery, as they could be prepared to take the matter further. He considered these arrangements beneficial, provided that they were not predatory. They could offer relief to creditors who were unable to continue fighting, while enabling a new buyer to pursue the debtor.
Mr. Galadari also explained that his firm considered enforcement and execution from the beginning of a dispute. This included examining the possibility of interim measures, applying pressure before an award was issued and securing assets at an early stage. He added that the firm sometimes funded its own cases or undertook matters on a contingency basis. Such arrangements demonstrated to external funders that the firm was willing to share the risk and remain committed to pursuing recovery. He concluded that the involvement of funders could create benefits for the original creditor, the new purchaser, and the broader recovery process.
Ms. Akter agreed that the involvement of a funder could create benefits beyond simply financing enforcement proceedings. She explained that the presence of a funder did not automatically result in a settlement but could increase the possibility of a negotiated resolution.
Referring to a recent anecdote, she described a settlement involving eight claims against a sovereign debtor. The claims varied in value and duration, with some having remained pending for approximately 10 years, while another had been financed only about a year earlier. She explained that the funder had developed an understanding of the debtor’s behaviour in litigation and its approach to negotiations over several years. This enabled it to assist eight different creditors in resolving their separate claims through a collective settlement.
Ms. Akter described this involvement like that of a mediator, since it was a third party without the emotional baggage or litigation fatigue experienced by the original creditors and had the financial capacity to pursue the debtor on several fronts simultaneously. She nevertheless acknowledged that the involvement of a funder could also lead to new disputes. A debtor might challenge the validity of the assignment agreement or raise other arguments affecting the amount or prospects of recovery. Accordingly, the involvement of a funder could create both opportunities and additional legal issues.
Panellists identify changes needed to strengthen the award monetisation market
In the last segment of the discussion, Mr. Agarwal invited the panellists to identify one change that could help the market for assignment and monetisation of arbitral awards:
-
Mr. Abdulla Galadari: Greater awareness of the recent legal developments by market participants which could help businesses understand the opportunities available.
-
Mr. Jonathan Huth: Involve enforcement lawyers and target the adversaries from the beginning of the dispute.
-
Mr. Ziad Obeid: Enforcement should not be treated as the final chapter of arbitration, rather recoverability should form part of the case strategy from the first day.
-
Ms. Sumru Akter: Alignment of expectations between buyers, sellers, and funders.
-
Mr. Farid Karachiwala: A more uniform international legal framework. He observed that the New York Convention did not expressly address the assignment of arbitral awards in a manner that would eliminate uncertainty. He suggested that a model universal legislation could clarify that awards were assignable and reduce the legal difficulties currently encountered in cross-border transactions.
Concluding the discussion, Mr. Agarwal reflected on the evolution of third-party funding and the increasingly nuanced issues surrounding awareness, collectability, and enforceability. He emphasised that the ultimate value of an award depended not merely on whether it had been obtained or could legally be transferred, but on whether it could actually be recovered.
1. The Market for ‘Lemons’: Quality Uncertainty and the Market Mechanism, 1970
2. Federal Decree by Law No. (25) of 2025 Promulgating the Civil Transactions Law
3. [2025] EWHC 2874 (Comm)
4. UNCITRAL, PCA Case No. 2008-13
5. Case No. 14-cv-01921 (CRC)
6. Republic of Cameroon v. CFS 37 Funding LP, Paris Judicial Court RG n° 26/80898