








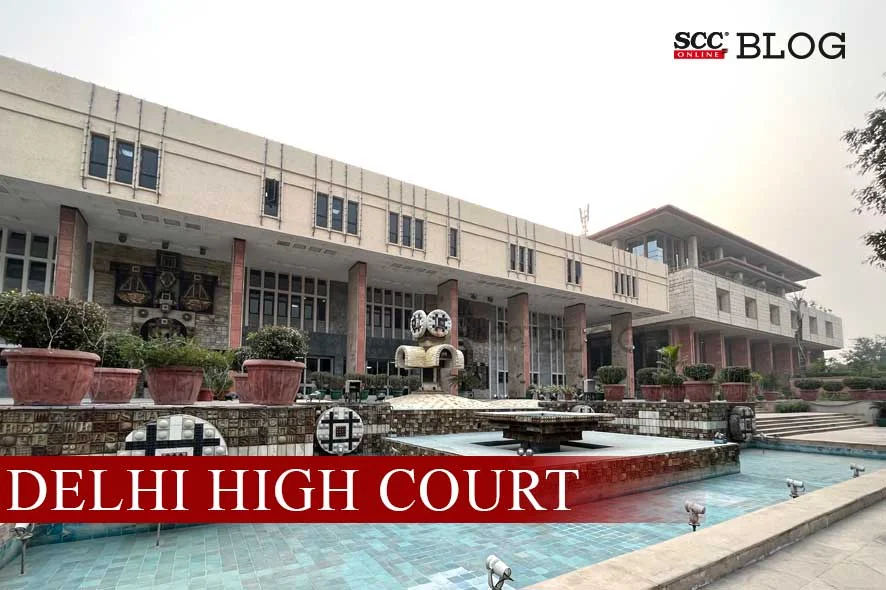
Delhi High Court: In a case wherein, the appeal was filed to challenge the order dated 30-12-2022, passed by the Income Tax Appellate Tribunal (‘the Tribunal’), the Division Bench of Rajiv Shakdher and Girish Kathpalia, JJ.*, agreed with the analysis and conclusion arrived by the Tribunal, that the services offered by the respondent to its Indian affiliates did not come within the purview of the Fees for Technical Services (‘FTS’), as reflected in Article 12(4)(b) of the India-Singapore Double Taxation Avoidance Agreement (‘India-Singapore DTAA’) and concluded that they did not fulfil the criteria of ‘make available’ principle.
Background
In the instant case, the Assessing Officer, via the draft assessment order dated 28-09-2021, concluded that the services provided by the respondent to the Indian subsidiary were in the nature of ‘management support services’ and hence were taxable at the rate of 10% plus surcharge and education cess under the India-Singapore DTAA. The respondent filed the objections before the Dispute Resolution Panel, but it was not successful.
Consequently, the final assessment order dated 30-03-2020, was passed by the Assessing Officer under Section 143(3) read with Section 144C(13) of the Income Tax Act, 1961 (‘the Act’). Thus, the respondent filed the appeal before the Tribunal.
The Tribunal was called upon to consider that with regard to the provisions of the India-Singapore DTAA, whether the income from ‘information technology and other administrative services’ provided by the respondent to its affiliate in India could be construed as FTS. The Tribunal held in favour of the respondent and stated that the services offered by the respondent to its Indian affiliates did not come within the purview of the FTS.
Thus, the appellant filed the present appeal.
Analysis, Law, and Decision
The Court referred to the impugned order dated 30-12-2022, wherein it was stated that in order to qualify as FTS, the services rendered ought to satisfy the ‘make available’ test. Mere incidental advantage to the recipient of services was not enough. The real test was the transfer of technology and in the present case, there was no transfer of technology. The Court observed that the Tribunal stated that the services offered by the respondent to its Indian affiliates did not come within the purview of the FTS, as reflected in Article 12(4)(b) of the India-Singapore DTAA and concluded that they did not fulfil the criteria of ‘make available’ principle.
The Court observed that according to the Tribunal, the agreement between the respondent and its affiliate had been effective from 01-01-2010, and as contended by the appellant, if technical knowledge, experience, skill, and other processes had been made available to the Indian affiliate, the agreement would not have run its course for such a long period.
Accordingly, the Court agreed with the analysis and conclusion arrived by the Tribunal and dismissed the present appeal.
[CIT (International Taxation) v. Bio-Rad Laboratories (Singapore) Pte Ltd., 2023 SCC OnLine Del 6770, decided on 03-10-2023]
Advocates who appeared in this case :
For the Appellant: Puneet Rai, Senior Standing Counsel with Ashivini Kumar and Rishabh Nangia, Advocates;
For the Respondent: Sashwat Bajpai, Advocate





3 replies