








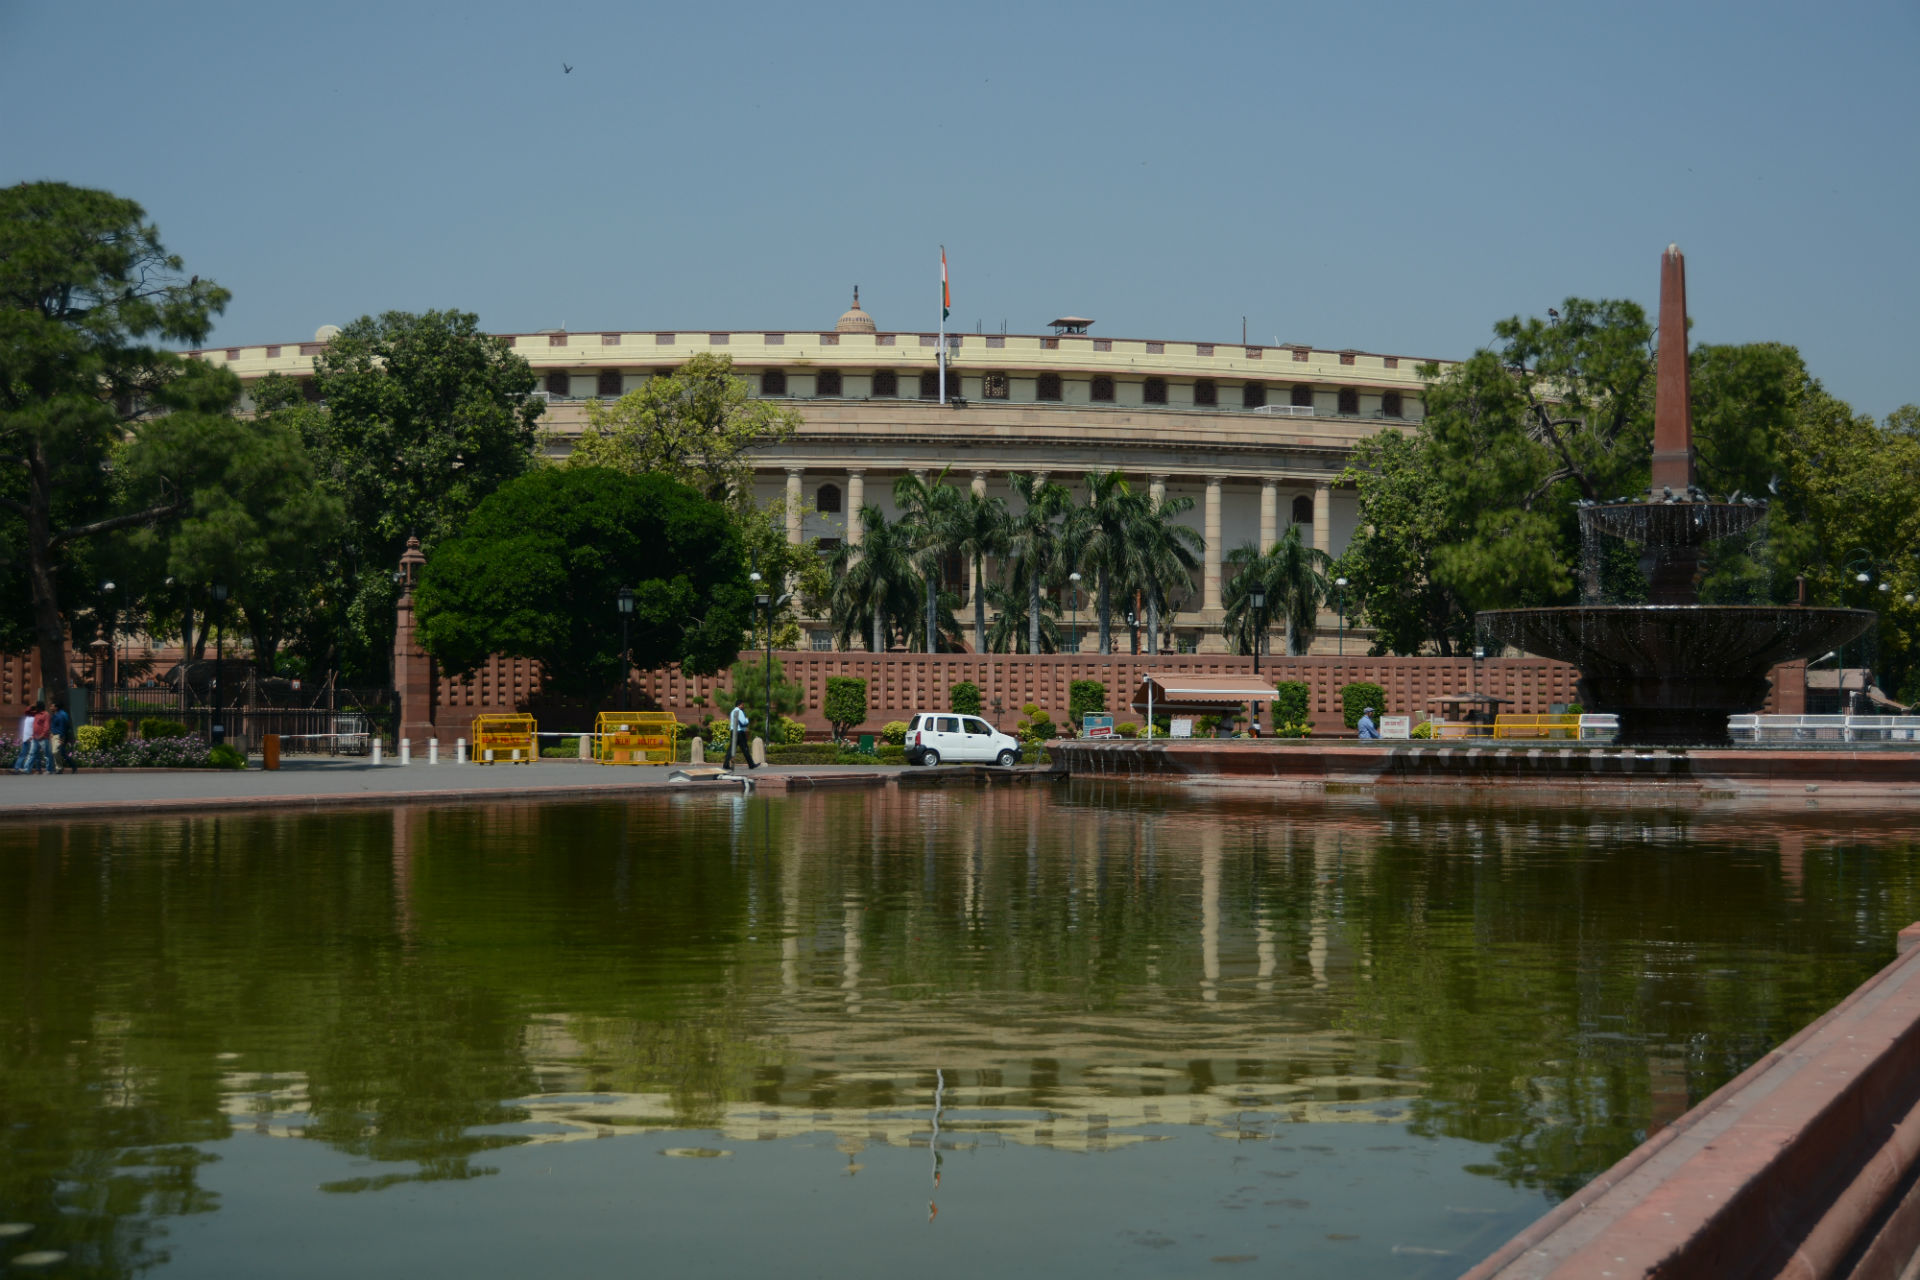
The Insurance Laws (Amendment) Bill, 2015 was passed by the Parliament on 12.03.2015. Earlier, the Bill was passed by Lok Sabha on 04.03.2015. The objective of the Bill is to remove archaic and redundant provisions in the legislations and incorporate certain provisions to provide Insurance Regulatory and Development Authority of India (IRDAI) with the flexibility to discharge its functions more effectively and efficiently. The Bill provides as follows:
- enhancement of the foreign investment cap in an Indian Insurance Company from 26% to an explicitly composite limit of 49% with the safeguard of Indian ownership and control.
- enable capital raising through new and innovative instruments under the regulatory supervision of IRDAI, which would lead to greater distribution reach to under / un-served areas in order to meet diverse insurance needs of citizens, efficient service delivery through improved distribution technology and enhanced customer service standards.
- enable the interests of consumers to be better served through provisions like penalties on intermediaries / insurance companies for misconduct, practice of mis-selling, misrepresentation by agents / insurance companies etc.
- easier process for payment to the nominee of the policy holder, as the insurer would be discharged of its legal liabilities once the payment is made to the nominee.
- obligation on insurance companies to underwrite third party motor vehicle insurance as per IRDAI regulations.
- IRDAI to regulate the eligibility, qualifications and other aspects of the appointments of insurance agents to insurers.
- IRDAI to regulate key aspects of Insurance Company operations in areas like solvency, investments, expenses and commissions and to formulate regulations for payment of commission and control of management expenses.
- empowers the Authority to regulate the functions, code of conduct etc., of surveyors and loss assessors.
- expands the scope of insurance intermediaries to include insurance brokers, re- insurance brokers, insurance consultants, corporate agents, third party administrators, surveyors and loss assessors etc.
- properties in India can now be insured with a foreign insurer with prior permission of IRDAI; which was earlier to be done with the approval of the Central Government.
- enables foreign reinsurers to set up branches in India and defines ‘re-insurance’ to mean “the insurance of part of one insurer’s risk by another insurer who accepts the risk for a mutually acceptable premium”, and thereby excludes the possibility of 100% ceding of risk to a re-insurer.any insurer or insurance intermediary aggrieved by any order made by IRDAI may prefer an appeal to the Securities Appellate Tribunal (SAT).
-Ministry of Finance





0 replies